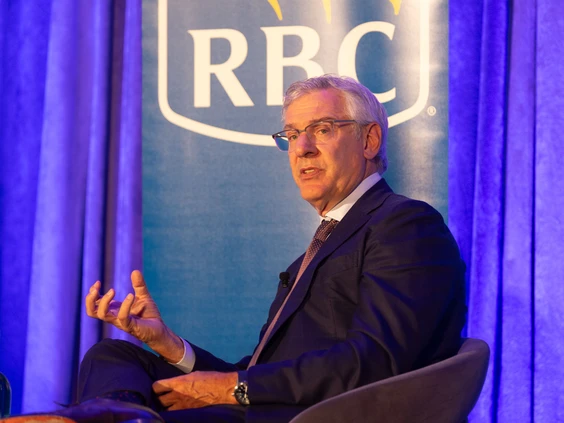
The head of Canada’s largest bank hopes Ottawa can eventually strike a long-term deal with Washington, as United States president Donald Trump escalated the ongoing trade war between the two countries by announcing new tariffs and bans on certain Canadian products.
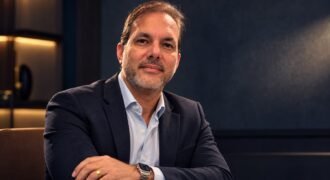
As the trade war expands, more people will pull back their spending, borrow less and try to manage their expenses, Royal Bank of Canada chief executive David McKay said at the Scotiabank Financials Summit conference on Wednesday.
Trump announced import bans and new tariffs on certain types of Canadian alcohol, dairy products, motorcycles and other kinds of products on Tuesday. The move is the latest step in an ongoing trade war between the two nations.
Despite the uncertainty in the economy caused by the ongoing trade war, each of Canada’s biggest banks comfortably beat analysts’ third-quarter earnings expectations last month, primarily due to a bump in their capital market business segments.
One reason why more capital is coming into Canada is the federal government’s desire to accelerate the growth of crucial energy-related projects, which would help Ottawa boost its economy and reduce the country’s reliance on the U.S. in the long run.
To further encourage growth, RBC announced a $1.4-billion initiative to invest in Canadian technology companies that have the potential to become global powerhouses. The lender will look to make direct equity investments in Canadian companies.
The banks also reported stable provisions for credit losses, which is the amount of money that lenders keep aside to tackle loans that may potentially go back, which means they’re generally confident about the near-term future.
RBC CEO hoping for a good long-term deal with the U.S., but Canadians showing resilience so far